


The homeowners insurance average price in the U.S. is roughly $2,400 to $2,900 per year in many 2026 studies. That equals about $200 to $240 monthly. Your actual premium can differ sharply because insurers price each property and policy differently.
Recent national estimates do not produce one universal figure. NerdWallet reports $2,490 yearly for $400,000 of dwelling coverage. Insurify reports $2,808 for a policy carrying $300,000 of dwelling coverage.
Quick answer: A typical U.S. homeowner may pay roughly $200 to $240 monthly for home insurance in 2026. Published averages differ because researchers use different coverage limits, deductibles, properties, locations, and insurer samples. The most useful benchmark therefore matches your home’s rebuilding cost and policy limits.
Home Insurance Cost at a Glance
| Cost measure | 2026 benchmark | Important context |
|---|---|---|
| NerdWallet national average | $2,490 yearly | $400,000 dwelling coverage |
| Insurify national average | $2,808 yearly | $300,000 dwelling coverage |
| Insurance.com national average | $2,872 yearly | $300,000 dwelling and liability coverage |
| Common monthly benchmark | About $200–$240 | Depends heavily on policy assumptions |
| Main price drivers | Location, rebuilding cost, coverage, deductible | Individual quotes can differ greatly |
These figures come from separate rate studies, so they should not be treated as identical measurements. Insurance.com, for example, reports $2,872 annually with $300,000 in dwelling coverage. Comparing the assumptions behind each number gives the average much more meaning.
Key Takeaways
- A practical 2026 national benchmark is roughly $2,400 to $2,900 per year.
- Published averages vary because researchers model different homes and coverage limits.
- Location can change a premium by thousands of dollars each year.
- Higher dwelling limits generally increase premiums because more property value is insured.
- A larger deductible may lower the premium but increases your potential out-of-pocket cost.
- Comparing equivalent quotes is more useful than comparing headline national averages.
What Homeowners Insurance Average Price Means in 2026
An average price is a benchmark, not a prediction of your personal premium. Each rate study builds a sample homeowner, property, deductible, and coverage package. Changing one assumption can substantially change the reported national figure.
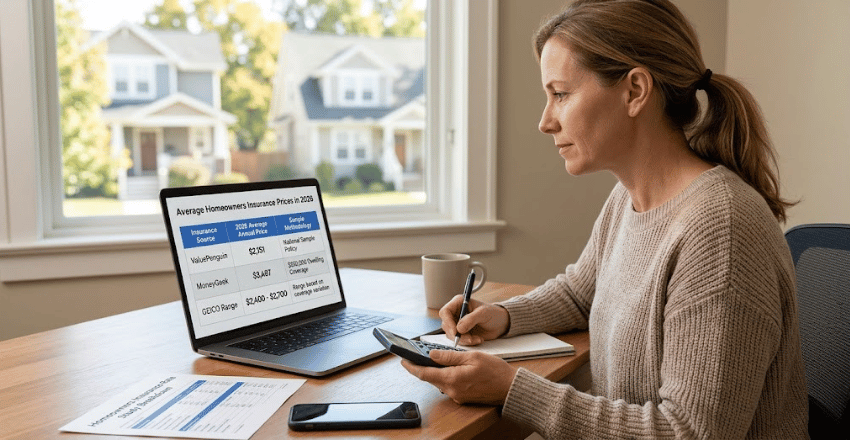
For example, ValuePenguin reports an average of $2,151 per year in its 2026 analysis. MoneyGeek reports $3,467 annually using $250,000 of dwelling coverage in its model. Those figures illustrate how methodology can produce different national averages.
GEICO describes a similar national range of roughly $2,400 to $2,700 annually. It also explains that varying coverage amounts and sample policies cause differences between published estimates. That makes methodology essential when comparing insurance statistics.
Why Home Insurance Prices Vary So Much
Your Location and Weather Risk
Your ZIP code can strongly influence what you pay. Insurers consider risks such as wind, hail, wildfire, hurricanes, theft, and local rebuilding expenses. Access to fire protection can also affect how a property is rated.
NAIC consumer guidance says location, construction, home age, coverage amount, and fire protection can affect premiums. Local crime conditions and access to emergency services may matter as well. These differences explain why two similar homes can receive different quotes.
Recent data shows the geographic gap can become extreme. NerdWallet lists Oklahoma among the costliest states in its 2026 analysis. Hawaii, Vermont, and Delaware sit among its lowest-cost states.
The Amount Needed to Rebuild Your Home
Dwelling coverage is usually based on rebuilding cost rather than the property’s sale price. Labor, roofing, lumber, fixtures, and local construction expenses all influence that estimate. A more expensive rebuild generally requires a larger policy limit.
The NAIC says dwelling coverage should be enough to fully rebuild the insured property. Replacement cost is different from market value because land value is not part of rebuilding the structure. Homeowners should review this limit as construction costs change.
That distinction matters when comparing premiums. A $500,000 market value does not automatically mean you need $500,000 of dwelling coverage. Your insurer or agent may use property characteristics and local construction data to estimate replacement cost.
Your Deductible
A deductible is the amount you pay toward a covered claim before insurance contributes. Selecting a larger deductible will often reduce your premium. It also increases the amount you must fund after a loss.
The NAIC confirms that lower deductibles generally produce higher premiums. Homeowners should choose an amount they could reasonably pay following unexpected property damage. Saving on premiums has limited value if the deductible becomes unaffordable.
Some policies also use percentage-based deductibles for specific disasters. Those deductibles can create much larger expenses than a standard fixed amount. Read the deductible provisions carefully before comparing policies.
Your Home’s Age and Construction
Older properties may cost more to insure when outdated systems increase claim risks. Electrical wiring, plumbing, roofs, and heating systems can influence underwriting. Some insurers may require updates before offering their preferred policy terms.
Recent NerdWallet research found a growing cost gap between older homes and newer construction. Its 2026 report found the modeled older property cost considerably more to insure than new construction. That gap reflects how property condition can influence expected losses.
Construction materials can also change risk. Fire resistance, roof type, storm protection, and structural features may influence pricing. Ask insurers which improvements qualify for discounts before spending money solely for insurance savings.
Why 2026 National Averages Disagree
Consider three current estimates side by side. NerdWallet reports $2,490 annually, Insurify reports $2,808, and Insurance.com reports $2,872. They are all credible benchmarks, yet their sample policies and datasets differ.
That difference is useful rather than contradictory. It shows why shoppers should compare policy assumptions before comparing prices. Coverage limits, deductibles, locations, credit profiles, and carrier samples can move the final average.
A homeowner should therefore avoid asking whether one national figure is perfectly correct. A better question asks whether the benchmark resembles the home being insured. Similar coverage assumptions make comparisons far more useful.
Average Price by Coverage Level
More dwelling coverage usually means a higher premium because the insurer accepts greater potential loss. Insurance.com’s 2026 data shows this relationship across several coverage levels. Its figures also show how deductibles can alter the result.
| Dwelling coverage | Example annual average | Example monthly average |
|---|---|---|
| $200,000 | About $2,156 | About $180 |
| $300,000 | About $2,872 | About $239 |
| Higher limits | Generally higher | Depends on insurer and property |
These numbers should be used as examples rather than quote estimates. Insurance.com uses defined liability limits and deductible assumptions in its comparisons. Your own property characteristics can move the price above or below them.
What Does a Standard Policy Usually Cover?
A typical policy can protect the dwelling, personal belongings, and liability exposure for covered events. It may also include additional living expenses after an insured loss. Exact protections and limits depend on the contract.
The NAIC explains that standard policies commonly cover the structure and personal belongings. They also commonly provide liability protection for covered injuries or damages. Policyholders should review exclusions and optional endorsements before assuming a risk is covered.
Flooding deserves special attention. Standard home policies generally do not cover flood damage, so separate flood protection may be necessary. FEMA states that homeowners typically need a separate flood insurance policy for that risk.
Replacement Cost Versus Actual Cash Value
Replacement cost coverage generally pays to replace covered property using comparable new materials, subject to policy terms. Actual cash value considers depreciation when calculating a covered loss. The difference can substantially affect a claim payment.
The NAIC explains that actual cash value subtracts depreciation based on age and wear. Replacement cost coverage generally does not make that depreciation deduction for comparable replacement. Understanding that distinction matters more than choosing a policy solely by premium.
A cheaper policy is not automatically a better deal. Lower premiums may accompany different settlement terms, deductibles, limits, or exclusions. Compare the protection you receive alongside the quoted price.
How to Lower Your Home Insurance Premium
Start by requesting comparable quotes from several carriers. Keep the dwelling limit, liability limit, deductible, and major endorsements consistent across each quote. Otherwise, a lower premium might reflect reduced protection rather than better pricing.
You can also ask about discounts for bundling insurance or installing qualifying security equipment. The NAIC notes that insurers may offer discounts for combining home and auto coverage. Some protective devices may also reduce premiums.
Consider a higher deductible only when you could comfortably cover it after a loss. Review the policy annually because rebuilding costs and household circumstances can change. Re-shopping periodically can also reveal meaningful pricing differences between insurers.
For more property-related reading, see Newpapero’s shared-property ownership guide on handling a co-owner who refuses a property sale. It explains another financial issue homeowners can face during shared ownership.
Home maintenance can also affect long-term property costs. Newpapero covers roofing considerations in its roofing membrane guide and window protection in its window grills guide. These topics can help owners think beyond the insurance bill itself.
How Much Should You Budget?
For a broad U.S. planning figure, budgeting around $200 to $240 monthly is reasonable before receiving quotes. That range reflects several major 2026 studies rather than one isolated estimate. High-risk locations can cost substantially more.
Use that amount only as an early household budget estimate. Your actual quote should replace the national benchmark once you start shopping. Build additional room into your budget if your property faces expensive weather or rebuilding risks.
Mortgage payments can also include the insurance premium through an escrow account. That arrangement changes how you pay, but it does not necessarily change the underlying policy price. Review your annual insurance documents even when your lender handles payment.
How to Compare Quotes Correctly
First, confirm that every insurer is pricing roughly the same dwelling limit. Next, compare liability limits, personal property coverage, deductibles, and replacement-cost provisions. Then review important exclusions and special disaster deductibles.
Do not rank quotes by premium alone. A policy costing $150 less yearly can become expensive after a claim if protection is meaningfully weaker. Price and coverage should be evaluated together.
Finally, confirm which discounts each company included. Ask whether those discounts continue after the first policy term. This prevents an introductory saving from distorting your long-term comparison.
Frequently Asked Questions
What is the homeowners insurance average price in the U.S.?
A useful 2026 benchmark is roughly $2,400 to $2,900 per year across several major studies. That equals approximately $200 to $240 per month. Different research methods prevent one national number from applying to every homeowner.
Why are homeowners paying more for home insurance?
Rising rebuilding expenses and catastrophe losses can put upward pressure on premiums. Local weather experience also influences pricing across states and regions. NerdWallet reported that its modeled U.S. premium rose 24% from early 2023 to early 2026.
Does a higher deductible lower home insurance costs?
A higher deductible can reduce the premium because you accept more initial claim expense. The NAIC confirms this general relationship between deductibles and premium levels. Choose a deductible that remains manageable during an emergency.
Is home insurance based on the home’s market value?
Not usually. Dwelling protection is generally tied to the cost of rebuilding the structure rather than its real estate sale price. Land value and local property demand can make market value quite different from replacement cost.
Does standard home insurance cover floods?
Standard policies generally exclude flood damage. Homeowners who need flood protection typically purchase separate coverage through the NFIP or another available insurer. Check your property’s risk and lender requirements before deciding.
How many home insurance quotes should I compare?
There is no mandatory number, but several comparable quotes give you a better picture of the market. Keep coverage limits and deductibles consistent while comparing them. A cheap quote with weaker coverage does not provide a fair comparison.
The Bottom Line
The homeowners insurance average price gives you a useful starting point, but it cannot predict your final bill. A practical 2026 U.S. benchmark is around $2,400 to $2,900 yearly. Location, rebuilding cost, deductible, property age, and coverage choices can move that amount substantially.
Use national averages to plan your budget, then replace them with real quotes for your property. Compare the same protection across multiple insurers before choosing a policy. The right target is affordable coverage that can still protect your finances after a serious loss.